
Overview
New York, NY – Oct 12, 2026 – The global Flame Arrestors Market is gaining importance as industries place greater emphasis on fire prevention, process safety, and the safe handling of flammable gases and vapors. Flame arrestors are safety devices designed to stop flame propagation through pipelines, storage tank vents, and industrial process systems while allowing gases or vapors to flow under specified operating conditions. These products are widely used in oil and gas facilities, chemical plants, refineries, pharmaceutical production, and bulk storage terminals.
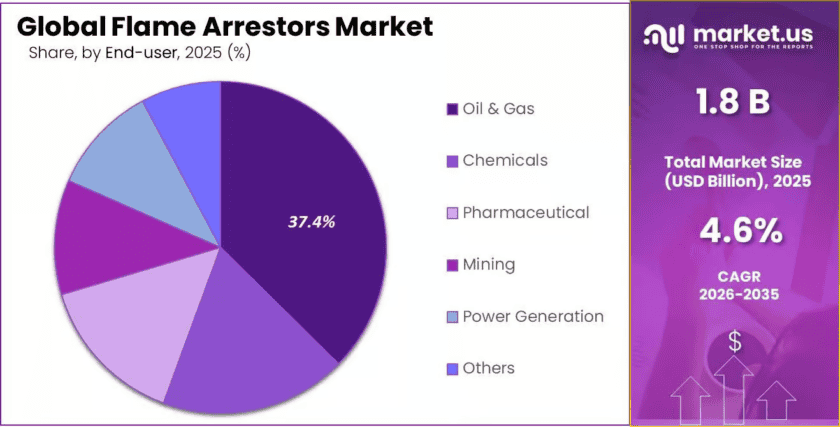
According to the supplied Flame Arrestors Market report, the market was valued at USD 1.8 billion in 2025 and is projected to reach USD 2.9 billion by 2035, reflecting a compound annual growth rate (CAGR) of 4.6% over 2025–2035. Inline arrestors led the type segment with a 63.00% share, while storage tanks accounted for 40.21% of application demand. Oil and gas represented 37.45% of end-user demand. North America dominated the regional landscape with a 34.21% share, equivalent to approximately USD 0.6 billion in revenue.
Industrial safety regulations, expansion of hydrocarbon infrastructure, and the need to control fire and explosion risks are supporting demand. The US Occupational Safety and Health Administration (OSHA) specifies approved flame-arrester or suitable venting requirements for certain flammable-liquid storage tanks, reinforcing the importance of correctly selected safety equipment.
Key Takeaways
- Market value: USD 1.8 billion in 2025.
- Projected value: USD 2.9 billion by 2035.
- Growth rate: 4.6% CAGR over 2025–2035.
- Leading product type: Inline arrestors, with a 63.00% share in 2025.
- Leading application: Storage tanks, accounting for 40.21% in 2025.
- Leading end user: Oil and gas, with a 37.45% share in 2025.
- Dominant region: North America, with a 34.21% share and approximately USD 0.6 billion in 2025 revenue.
Regional Analysis
North America held the leading position in 2025, capturing 34.21% of the market and generating approximately USD 0.6 billion in revenue. Its large oil and gas, petroleum refining, and chemical-processing industries create demand for flame arrestors across storage tanks, pipelines, and vapor-handling systems. OSHA’s flammable-liquid rules provide a regulatory basis for using approved flame arresters or appropriate venting arrangements in certain tank applications.
Europe benefits from established process industries, industrial safety requirements, and demand for reliable protection in chemical manufacturing and petroleum storage. Equipment selection and maintenance remain important because flame arrestors must match the gas or vapor, operating conditions, and potential flame-propagation scenario.
Asia-Pacific offers opportunities through expanding industrial facilities, energy infrastructure, chemical production, and storage capacity. Demand will depend on the pace of investment, safety enforcement, and the adoption of suitable flame-protection systems.
Latin America is supported by oil and gas operations, refining facilities, and bulk-liquid storage requirements. The Middle East and Africa also present opportunities associated with hydrocarbon processing, terminals, and industrial infrastructure. Across these regions, actual growth depends on project investment, equipment standards, and maintenance practices.
Market Dynamics
1. Driver: Rising Focus on Industrial Fire and Explosion Prevention
Industrial fire prevention is a major driver for the Flame Arrestors Market. Oil refineries, chemical plants, and storage terminals handle flammable liquids and vapors that can create dangerous conditions if ignition occurs.
Flame arrestors help prevent flames from travelling through connected pipelines or vent systems when properly selected and installed. OSHA requires approved flame arresters or specified venting protection for certain tanks containing Category 2 and some Category 3 flammable liquids. These requirements encourage operators to review their existing safety equipment, replace unsuitable devices, and install compliant systems when facilities are upgraded.
2. Trend: Better Integration with Modern Process-Safety Systems
Industrial operators increasingly consider flame arrestors as part of an overall process-safety system rather than as isolated components. Equipment selection must account for gas composition, pressure, temperature, flow rate, and the possibility of deflagration or detonation. Inspection planning and monitoring of pressure drop can help identify blockage or maintenance needs.
The US Environmental Protection Agency’s storage-vessel standards also address volatile organic compound emissions from facilities handling organic liquids. This creates an overlapping need to manage both vapor emissions and ignition risks. Manufacturers can respond through improved designs, material choices, and clearer maintenance guidance.
3. Restraint: Maintenance Requirements and Pressure-Drop Concerns
High initial costs, installation complexity, and ongoing maintenance can limit flame-arrester adoption, particularly at smaller industrial facilities. Arrestor elements may become blocked by corrosion products, dust, deposits, or process residues, restricting gas flow and increasing pressure drop.
An incorrectly selected device can also create operating problems or fail to provide the required protection. Operators must consider inspection access, compatible materials, operating conditions, and replacement needs before installation. OSHA’s tank-venting provisions show that flame arresters cannot be selected independently of the wider venting arrangement. These engineering and maintenance requirements can increase ownership costs and extend project implementation timelines.
4. Opportunity: Modernization of Storage and Vapor-Control Infrastructure
Industrial facility upgrades create opportunities for manufacturers of flame arrestors, particularly where older storage tanks, vapor lines, and process equipment require improved safety protection. The US Environmental Protection Agency finalized updated storage-vessel emissions standards on October 15, 2024, addressing volatile organic compound emissions from covered storage vessels.
Although these rules do not mandate flame arrestors for every installation, they encourage operators to review vapor-handling and control arrangements. Equipment suppliers can benefit by offering application-specific arrestors, corrosion-resistant designs, inspection services, and replacement components. Demand opportunities are strongest where industrial upgrades combine emissions management with documented fire and explosion risk controls.
Emerging Trends
1. Improved Inline Flame-Arrestor Designs
Inline arrestors accounted for 63.00% of the market in 2025, according to the supplied report. Their use in process pipelines encourages manufacturers to improve flame-quenching elements while maintaining required flow capacity and compatibility with industrial operating conditions.
2. Increased Attention to Tank-Vent Protection
Storage tanks represented 40.21% of application demand in 2025. Operators are reviewing tank venting, pressure relief, and ignition protection as part of facility safety programs. OSHA specifies approved flame-arrester or suitable venting arrangements for certain flammable-liquid tanks.
3. Corrosion-Resistant Materials
Manufacturers are focusing on materials suited to corrosive vapors, humid environments, and demanding process conditions. Better material selection can extend service life and reduce maintenance interruptions. OSHA also identifies corrosion-resistant materials as one option for protecting tanks and associated piping.
4. Combined Vapor and Emissions Management
Flame-arrester selection is increasingly considered alongside vapor-control requirements. The US EPA’s storage-vessel standards address volatile organic compound emissions and apply to covered facilities handling organic liquids. This encourages coordinated planning for safe vapor handling, emissions control, and ignition-risk reduction.
5. Stronger Inspection and Maintenance Planning
Industrial operators are giving greater attention to checking arrestor elements for deposits, corrosion, and excessive flow restriction. Planned inspections help identify maintenance needs before performance deteriorates. Equipment documentation and appropriate inspection intervals remain important for safe, reliable operation.
Use Cases
1. Petroleum Storage Tanks
Flame arrestors can protect suitable tank vent systems where flammable vapors may be present. They help prevent flame propagation through a vent when correctly specified. OSHA addresses approved flame arresters and venting protection for certain flammable-liquid storage tanks.
2. Oil and Gas Processing Pipelines
Inline flame arrestors are used in appropriate gas and vapor lines to reduce the risk of flame travelling between connected equipment. The market report assigns oil and gas a 37.45% end-user share in 2025, reflecting the importance of this industrial application.
3. Chemical Manufacturing Plants
Chemical facilities may handle solvents and other flammable substances during mixing, separation, storage, and transfer. Flame arrestors can be installed in suitable process or vent lines after an engineering assessment of the vapor, operating conditions, and possible ignition scenarios.
4. Pharmaceutical Production and Solvent Handling
Pharmaceutical manufacturing may involve flammable cleaning agents, solvents, and process vapors. Where a risk assessment identifies flame-propagation hazards, appropriately rated arrestors can form part of the engineered protection system. Device selection must match the actual process and applicable safety requirements.
5. Waste-Gas and Incineration Systems
Some industrial waste-gas and vapor-treatment systems require protection against flame travelling back through connected lines. A suitable arrestor may be used where the equipment design and operating conditions permit it. Engineers must consider gas composition, temperature, flow, and the relevant safety standards.
Frequently Asked Questions
1. What is the Flame Arrestors Market size in 2025?
According to the supplied market report, the global Flame Arrestors Market was valued at USD 1.8 billion in 2025. Demand is linked to industrial fire protection, flammable-vapor handling, and process-safety requirements.
2. What is the projected market value by 2035?
The market is projected to reach USD 2.9 billion by 2035, according to the supplied report. This forecast reflects expected demand from industrial storage, pipelines, chemical processing, and other facilities requiring flame-propagation protection.
3. What is the expected CAGR of the Flame Arrestors Market?
The supplied report estimates a 4.6% CAGR over 2025–2035. This growth outlook reflects industrial safety needs, investment in process infrastructure, and the use of flame arrestors in suitable gas and vapor-handling applications.
4. Which product type leads the market?
Inline arrestors led the market in 2025, accounting for 63.00% of the reported share. These devices are installed in suitable pipelines and process lines to help stop flame propagation while allowing normal gas or vapor flow.
Conclusion
The Flame Arrestors Market is positioned for steady expansion, with the supplied report projecting growth from USD 1.8 billion in 2025 to USD 2.9 billion by 2035, at a 4.6% CAGR. Demand is supported by industrial fire prevention, storage-tank safety, pipeline protection, and the handling of flammable gases and vapors.
Inline arrestors, storage tanks, and oil and gas applications represent the leading segments, while North America remains the dominant region. Future opportunities will depend on industrial infrastructure investment, effective safety enforcement, equipment modernization, and proper maintenance. Manufacturers that provide reliable, application-specific products can serve evolving industrial protection requirements.
Discuss your needs with our analyst
Please share your requirements with more details so our analyst can check if they can solve your problem(s)